

Jurisdictions
One platform. Local rules. Global visibility.
R&D incentives exist across most of the world's innovation economies — but the rules, rates and evidence requirements change at every border. We bring them together on one platform, with local expertise in each market.

Where we Work
Hover for the country. Click to open its row below.
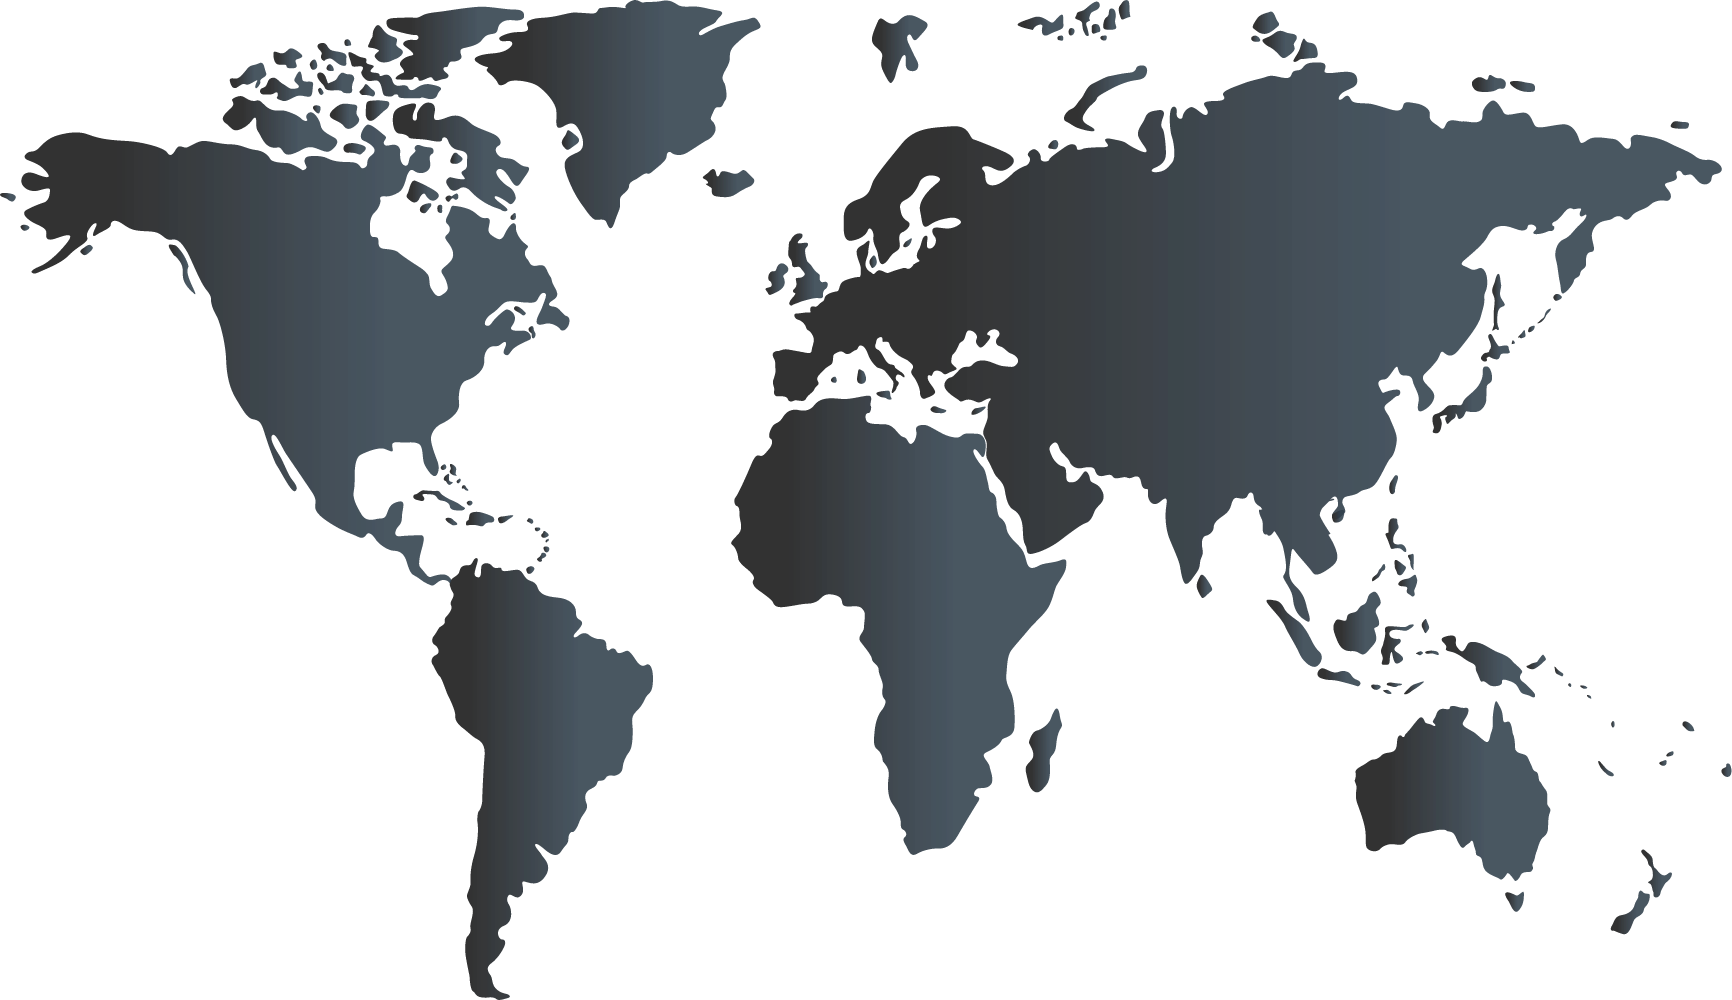
Every regime rewards the same thing: work that resolves technical uncertainty.
What differs is how each country defines it, caps it, pays it and polices it. That's the part we handle.
Main areas we cover
Click a row for what matters and what it’s worth
- Four-part test, applied per business component — at least 80% of the activity must be experimentation.
- From TY2025, Form 6765 Section G demands business-component detail, with wages split by research, supervision and support.
- That detail is hard to rebuild at year end. It has to be captured as the work happens.
- 20% regular credit above a base, or 14% ASC above half the prior three-year average.
- Non-refundable federally — carry back one year, forward twenty. Cash still arrives: look-back refunds for open years, carrybacks, and up to $500k a year against payroll tax for start-ups.
- Domestic R&D fully deductible again from TY2025. State credits stack, and some are refundable.
- Two-part test: an advance sought where uncertainty exists, pursued by systematic investigation. Work that fails still qualifies.
- Hard deadline — 18 months after year end. The CRA cannot extend it.
- Voluntary pre-claim approval now gives certainty before you file.
- 15% basic credit; 35% enhanced and fully refundable on up to $6M for CCPCs and eligible public companies (tax years from 16 Dec 2024).
- Capital expenditure is eligible again.
- Provincial credits stack on top.
- An advance in science or technology by resolving uncertainty — judged against what a competent professional could readily work out.
- Two gates that void a claim if missed: a claim notification within six months of period end if new to claiming, and the Additional Information Form with the claim.
- Overseas subcontractor and worker costs largely excluded.
- Merged RDEC at 20% above the line — about 15% net at the main rate.
- ERIS for loss-making SMEs with R&D at 30%+ of spend: an 86% extra deduction plus a 14.5% payable credit, around 27% of qualifying spend.
- Paid in cash to loss-makers, net of notional tax. Data and cloud costs eligible.
- Systematic, investigative or experimental work seeking a scientific or technological advance.
- Pre-filing notification at least 90 days before a first claim, or after three years without one.
- Claim within 12 months of period end — statutory, no extensions — with dated, contemporaneous records.
- 35% for accounting periods beginning on or after 1 January 2026 (30% before).
- Paid in three instalments over three years; first-year amounts up to €87,500 paid in full.
- Cash or offset — the company chooses at each instalment.
- Core R&D (hypothesis → experiment → evaluation) versus supporting activities, which must directly relate and often pass a dominant-purpose test.
- Register with AusIndustry within 10 months of year end — a separate step from the tax claim.
- Contemporaneous evidence is what holds the core/supporting line under review.
- Under $20M turnover: refundable offset at the corporate rate + 18.5 points (43.5%).
- Above: non-refundable offset at the corporate rate + 8.5 points, rising to 16.5 above 2% R&D intensity.
- $20,000 minimum spend; $150M notional deduction cap.
- Basic research, industrial research or experimental development — judged on novelty, technical risk and method, not commercial outcome.
- A BSFZ certificate for the project comes first; the claim then goes to the tax office.
- Open to any company liable to German tax, in any sector, profitable or not.
- 25% of eligible costs; 35% for SMEs.
- From 2026: a €12M annual base plus a 20% overhead uplift — up to €4.2M a year for SMEs, €3M for others.
- Paid out where it exceeds tax due. Contract research in the EEA counts at 70%.
- Genuine research judged against the state of the art, with project-level technical files and time records by project.
- Optional advance ruling (rescrit), filed at least six months before the declaration deadline.
- Three-year assessment window.
- 30% of eligible spend to €100M, 5% above, no overall cap.
- Immediate cash refund for SMEs, young innovative companies and new companies; others offset over three years, then paid.
- Innovation credit for SMEs: 20% on up to €400k, to end-2027. Staff overhead rate now 40%.
- OECD Frascati test — novel, creative, uncertain, systematic, reproducible — and the work must happen in the UAE.
- Pre-approval from the Emirates Research and Development Council is mandatory; spend before approval may not count.
- Headcount thresholds at each tier: 2, 6 and 14 R&D staff.
- 15% on the first AED 1M, 35% to AED 2M, 50% to AED 5M — about AED 2M maximum per entity per period.
- Non-refundable: offsets corporate and top-up tax; unused credit carries forward.
- Minimum AED 500k per project. Tax periods from 1 January 2026.
- The general rate moves with R&D intensity and its year-on-year change, not a fixed percentage.
- IP from the work must sit with the Japanese taxpayer — a trap for groups holding IP centrally.
- Overseas premises excluded; outsourced overseas R&D counts only in part from April 2026.
- General credit of 1–14% of R&D spend, capped at 25% of corporate tax, with headroom for rising intensity.
- New strategic technology credit: 40% (50% for special priority research) on AI, semiconductors, quantum and related fields, capped at a further 10%.
- Offsets tax only. Certification for the strategic credit opens FY2027.
Figures current as of October 2026 and simplified for comparison. Rates, caps and deadlines change — talk to us about your period.
One business. Multiple regimes. One source of truth.
A US-headquartered company with engineers in California, Toronto, London and Dublin. Traditionally that means four advisors, four questionnaires, four data sets — and four different answers to the same question about the same work.

Capture once.
Project, technical, employee and financial information enters one framework, as the work happens.
Apply locally.
Each activity is assessed against the rules of its own jurisdiction.
Reward globally.
One view of the R&D incentive position across every country — and every entity in the group claims what its own jurisdiction rewards.
Support continuously.
The evidence behind each claim is kept as it is created, not rebuilt at year end.
Don't see your country listed?
If your government offers an R&D incentive, there's a good chance we can help you claim it.